



By Chr. Christodoulou-Volos
- Professor of Macroeconometrics and Finance
- Chair of the Department of Economics and Management at Neapolis University Pafos
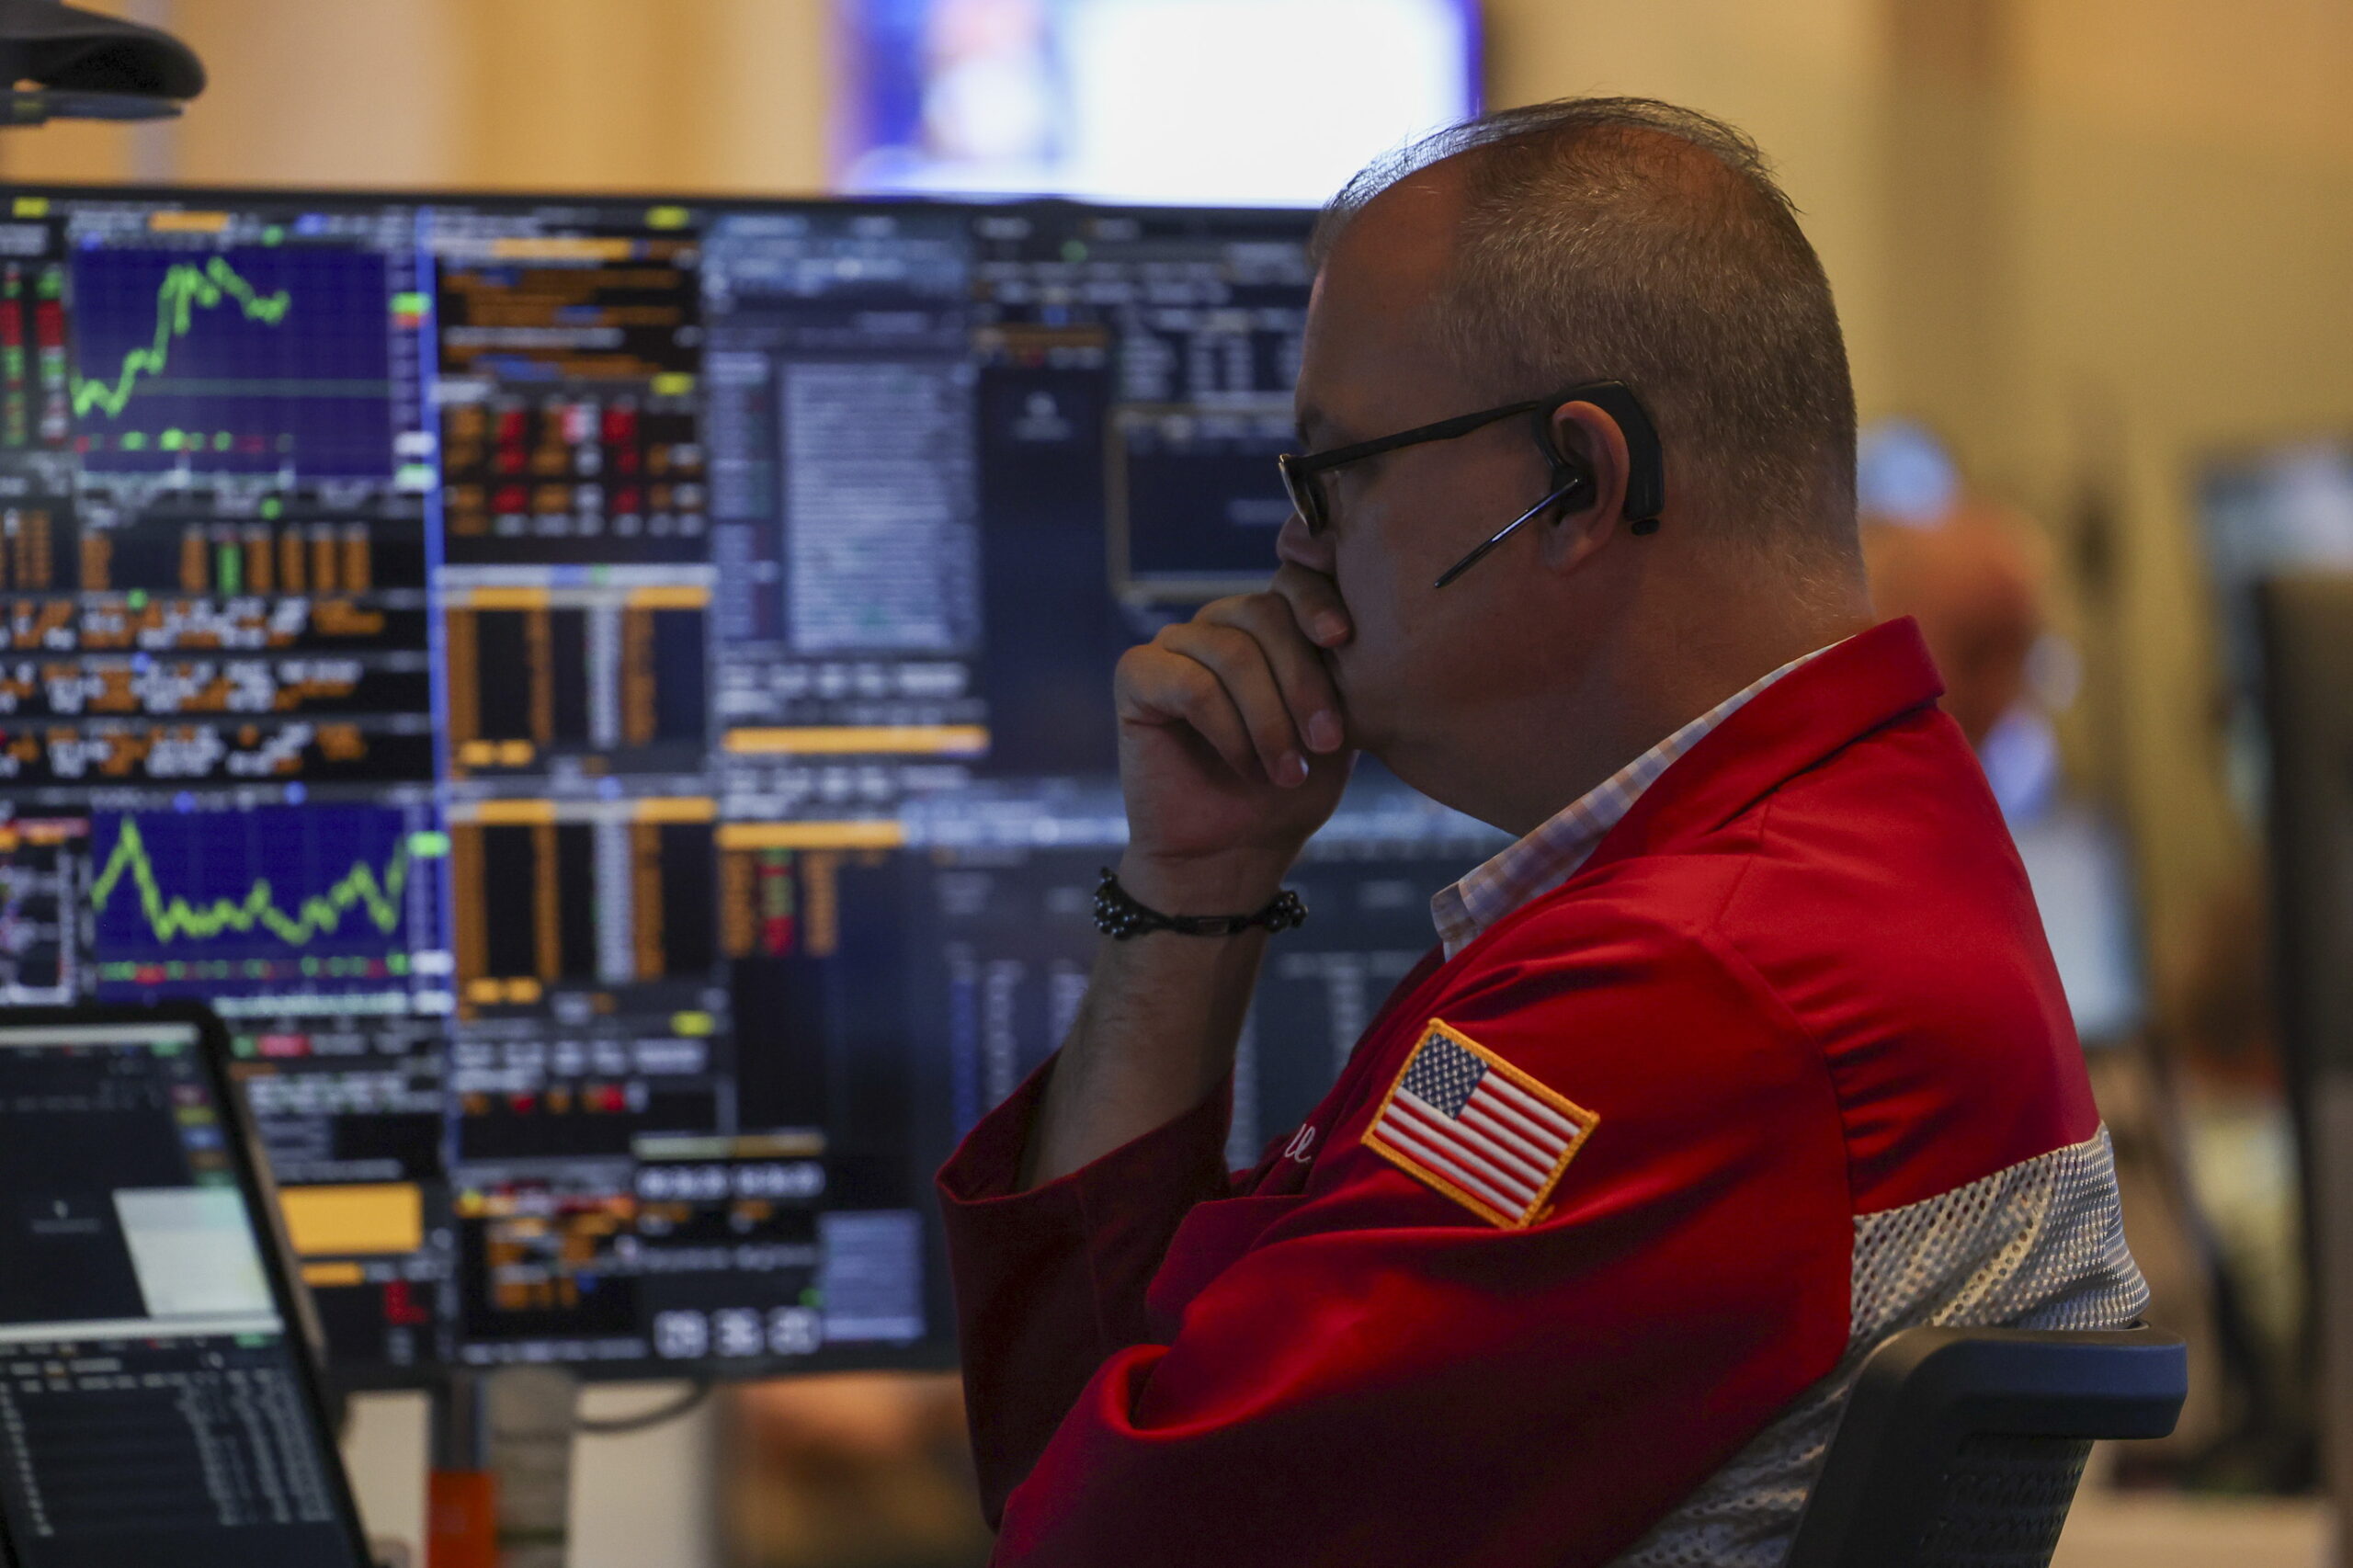
The size of the U.S. public debt is staggering, having surpassed the historic threshold of 40 trillion dollars for the first time. This figure is not merely an impressive statistical milestone. It reflects a deeper fiscal imbalance that could affect the U.S. economy, international financial markets, the European Union, and ultimately global economic stability.
ΣΧΕΤΙΚΑ ΑΡΘΡΑ

U.S. debt soars: It has exceeded $40 trillion for the first time
The rise in debt is linked to the U.S.’s long-standing inability to curb budget deficits, as well as to the rising cost of servicing the debt. Increased spending on health care and social security, combined with higher yields on U.S. Treasury bonds, creates a vicious cycle: the higher the debt, the higher the interest payments, and, consequently, the greater the need for new borrowing.
Particularly alarming is the fact that the debt now stands at approximately 125% of U.S. GDP, whereas about two decades ago it was close to 64%. At the same time, the federal deficit remains persistently high, indicating that the problem is not cyclical but structural.
The Implications for the U.S.
The rise in debt does not mean that the U.S. is immediately facing a debt crisis similar to those experienced by other countries. The dollar remains the dominant international reserve currency, and U.S. Treasury bonds are still considered a key safe haven.
However, this situation is gradually limiting the U.S. government’s fiscal space. The larger the portion of the budget allocated to interest payments, the fewer resources remain for investment, infrastructure, education, technology, or other public policies. At the same time, an increased supply of government bonds can keep borrowing costs higher and affect private-sector investment.
What does this mean for the European Union?
For the European Union, the consequences are particularly significant. A prolonged rise in U.S. interest rates and bond yields could trigger a flight of capital to the U.S., increasing pressure on European financial systems.
At the same time, a stronger dollar could make imports into Europe more expensive—particularly energy and raw materials priced in dollars—creating additional inflationary pressures. For the European Central Bank, this complicates the conduct of monetary policy, as it must strike a balance between the need to support growth and the need to counter potential inflationary pressures.
The rest of the world is not unaffected
The significance of U.S. debt extends far beyond the borders of the United States. The dollar is at the core of the international financial system, and U.S. Treasury bonds occupy a central position in the reserves of many countries and in international investments.
Therefore, a sharp rise in yields or a loss of confidence in U.S. fiscal policy could cause turmoil in international markets, raise financing costs worldwide, and increase volatility in exchange rates and bond markets.
The real issue, therefore, is not merely that U.S. debt has surpassed $40 trillion. It is that the world’s largest economy continues to increase its debt at a rate that can hardly be considered sustainable in the long term.
U.S. debt is now a global economic warning sign. As long as the dollar and U.S. Treasuries maintain their dominant position, the U.S. has significant leeway. However, economic history reminds us that confidence is not inexhaustible. Fiscal adjustment is no longer just an American issue; it concerns the entire global economy.











